 chapter
Chapterwise retirement guide
The Launch That Takes Longer Than Expected
Nearly 1 in 5 Canadian households includes an adult child living with parents. Here's how to support them without derailing your own retirement.
The plan used to have a fairly predictable shape: raise the kids, launch them somewhere around 18 or 22, then turn your attention back to your own life and your own retirement. For a lot of families today, that plan has a longer runway than it used to, and the launch itself takes longer, sometimes much longer, than anyone expected.
This isn't a fringe situation. Nearly one in five Canadians lived in an intergenerational household with adult children in 2021, and the pattern is especially common through the university and early career years: more than half of 20 to 24 year olds still live with a parent, and even among 25 to 29 year olds, roughly a quarter do too. Add in the growing "boomerang" pattern, adult kids who move out and then move back, often after a layoff, a breakup, or simply the math of rent not working, and it's clear this stretch of parenting doesn't wrap up as cleanly as it once did.
Why this chapter deserves its own plan
It's easy to treat a kid still at home, or back at home, as a temporary inconvenience rather than a genuine chapter worth planning for. But the financial shape of this stretch is real. Housing, groceries, insurance, and general household costs don't shrink just because the "kids" in question are technically adults. And unlike the earlier parenting years, this chapter often arrives at the exact moment your own retirement planning should be picking up speed, not slowing down to cover another few years of full household costs.
Surveys of parents supporting adult children consistently point to the same tension: a large share say the experience is affecting their own long-term savings, and most never explicitly planned for this phase the way they planned for daycare or braces or a first car years earlier.
What a successful launch actually needs
None of this means the answer is to stop helping. A launch that goes well usually isn't about withdrawing support. It's about making the support intentional rather than open-ended.
- A shared understanding of what the stay is for. Whether it's finishing a degree, saving for a first apartment, or getting back on their feet after a setback, naming the purpose out loud, together, turns an open-ended arrangement into a chapter with a clear direction.
- Some financial participation, even modest. This isn't about extracting rent for its own sake. Even a small, symbolic contribution toward groceries or utilities helps build the habits and confidence a young adult will need once they're fully on their own, and it protects the relationship from quietly becoming a source of resentment on either side.
- A rough sense of timeline, revisited rather than fixed. A completely open-ended arrangement can drift for years without anyone quite deciding it should. A loose target, tied to a milestone rather than a rigid date, gives everyone something to work toward without turning the conversation into an ultimatum.
- Your own plan staying in the room. It's worth being honest, with yourself and eventually with your kids, about what you can actually afford to provide without meaningfully denting your own retirement. Generosity that quietly borrows from your own future isn't sustainable generosity, even when it comes from the best intentions.
A smaller first step
Try the decision before you sign up
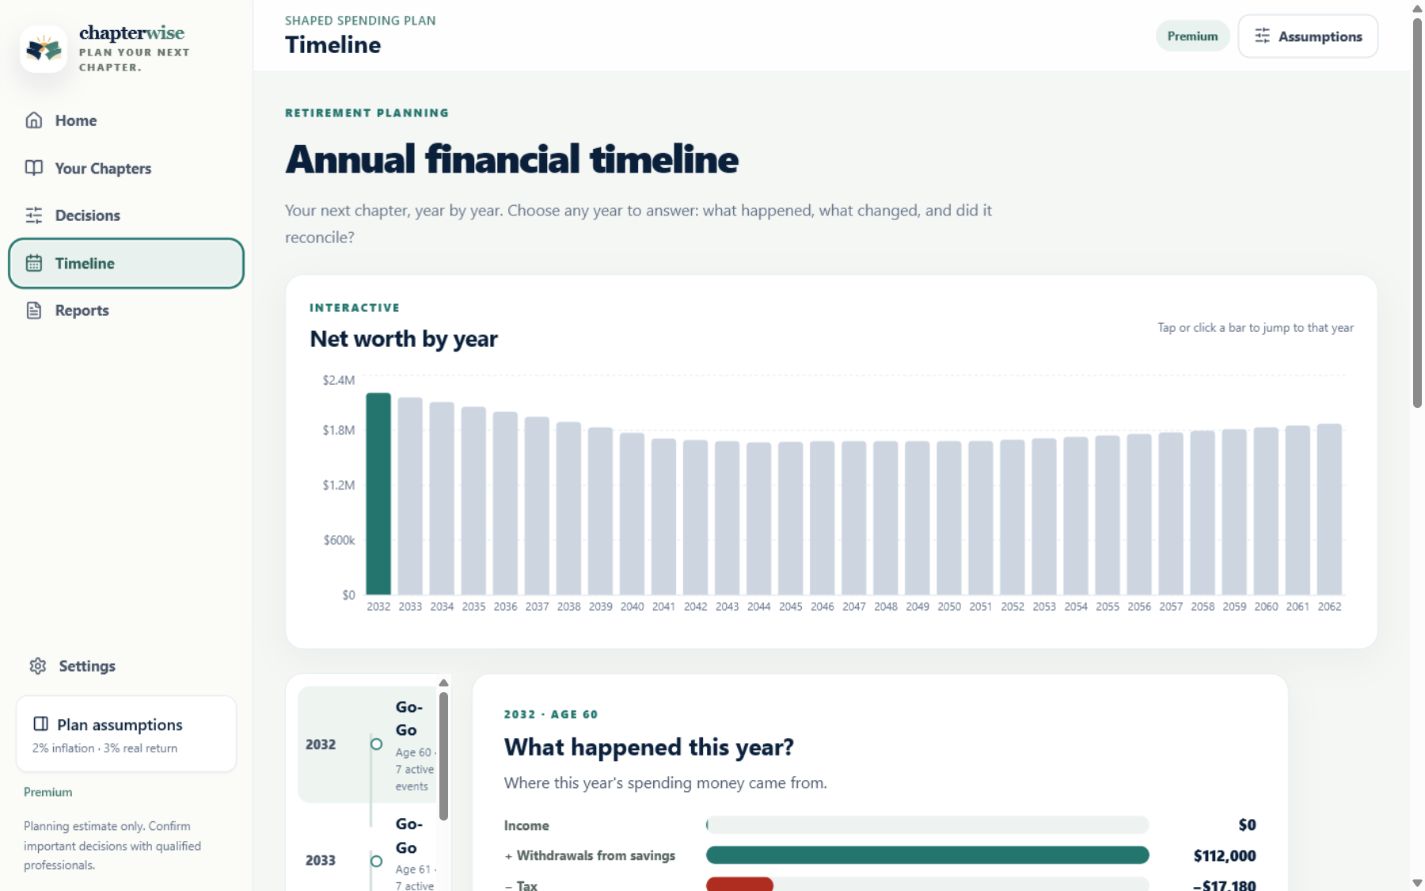
This directional preview reuses the same illustrative logic as the homepage. It is not a recommendation or a personalized projection.
Helping without losing your own chapter
Supporting an adult child through a longer, messier launch than either of you expected isn't a failure of planning. It's simply a more common shape for this chapter than it used to be. The families who navigate it best tend to treat it the way they'd treat any other significant chapter: with an honest conversation, a rough shared plan, and enough attention to make sure two futures, yours and theirs, are both still being written, not just one.
This article is for general educational purposes and describes a common pattern among Canadian families. It isn't personalized financial or family advice.