 chapter
Chapterwise retirement guide
The Chapter Where Saving Turns Into Spending
Your RRSP must convert to a RRIF by age 71. Here's what that means, when to convert earlier, and how to avoid a tax surprise.
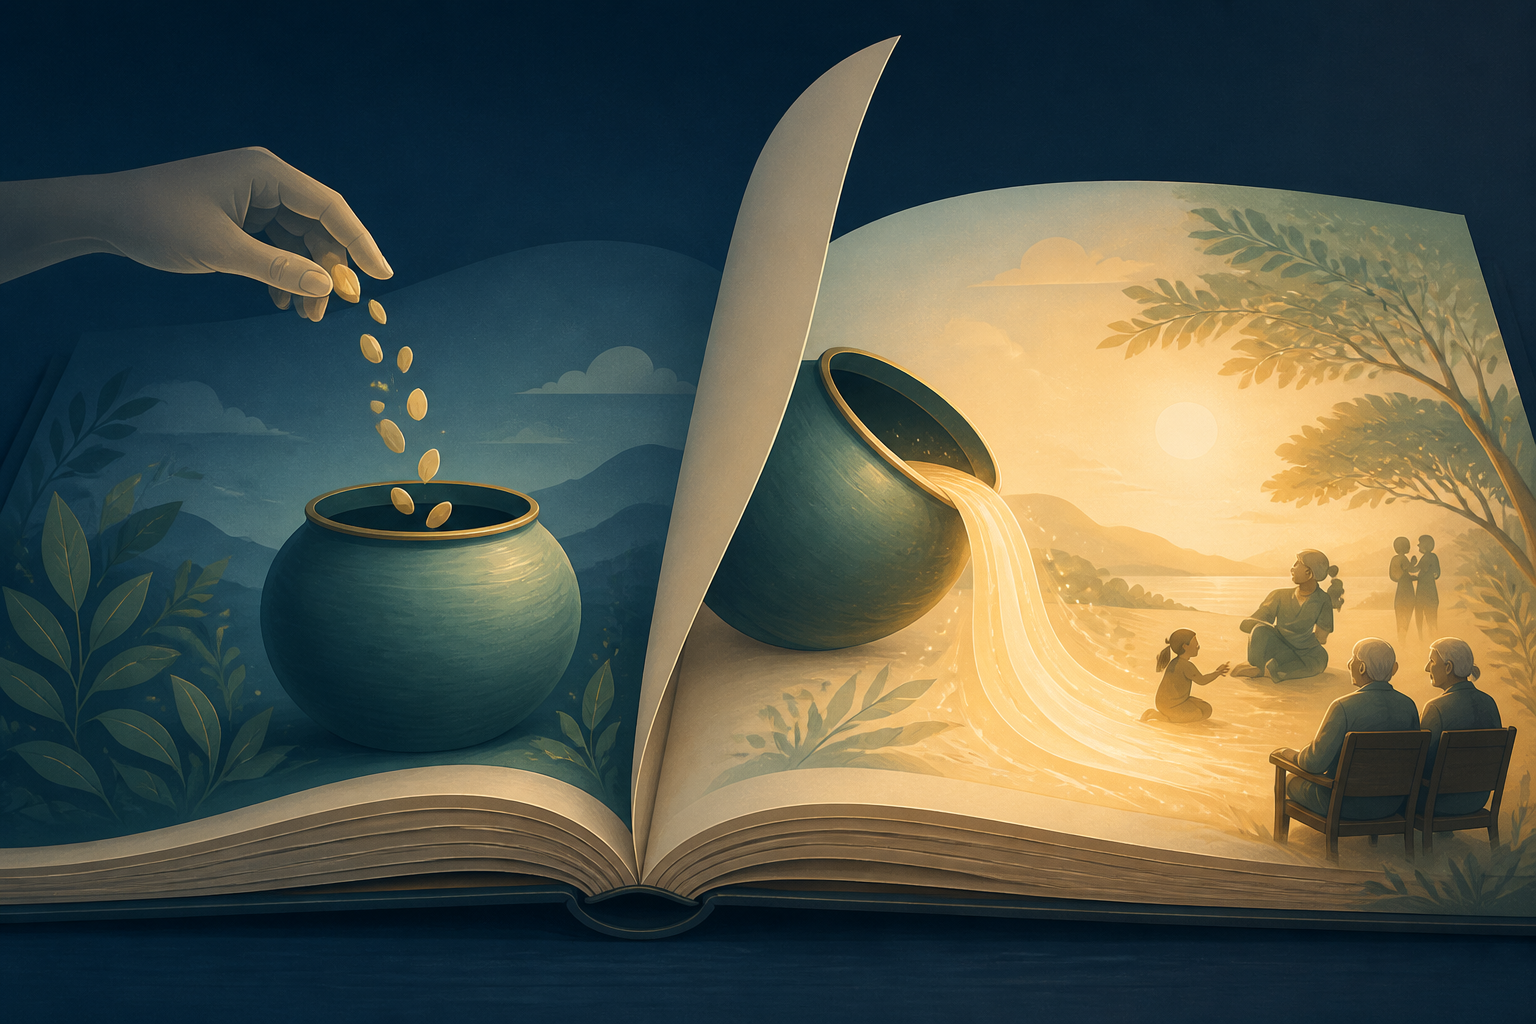
For decades, the RRSP plays one role in the story: a place things go in. Every contribution is another line added to a chapter about building, saving, growing. And then, at a specific point, the story requires a turn. The account that spent thirty years accepting deposits has to become one that pays out.
In Canada, that turn isn't optional. An RRSP has to convert to a RRIF, an annuity, or be cashed out by the end of the year you turn 71. Once it becomes a RRIF, minimum withdrawals begin the following year, whether you need the income yet or not.
Why this chapter deserves attention before it arrives
Because the deadline is fixed, it's tempting to treat it as something to deal with when it comes up. But the years leading up to 71 are often where the real decisions live. A RRIF can actually be started earlier, any time after an RRSP holder turns 65, and for some people that's a genuinely useful move, not a forced one.
Converting earlier can open access to the pension income tax credit and to pension income splitting with a spouse, both of which are only available once the income is flowing through a RRIF rather than sitting in an RRSP. It can also be a deliberate way to draw down savings gradually in lower-tax years, before CPP and OAS start layering on additional income, rather than facing a much larger mandatory withdrawal later once the balance has kept growing.
Why the timing matters more than it looks
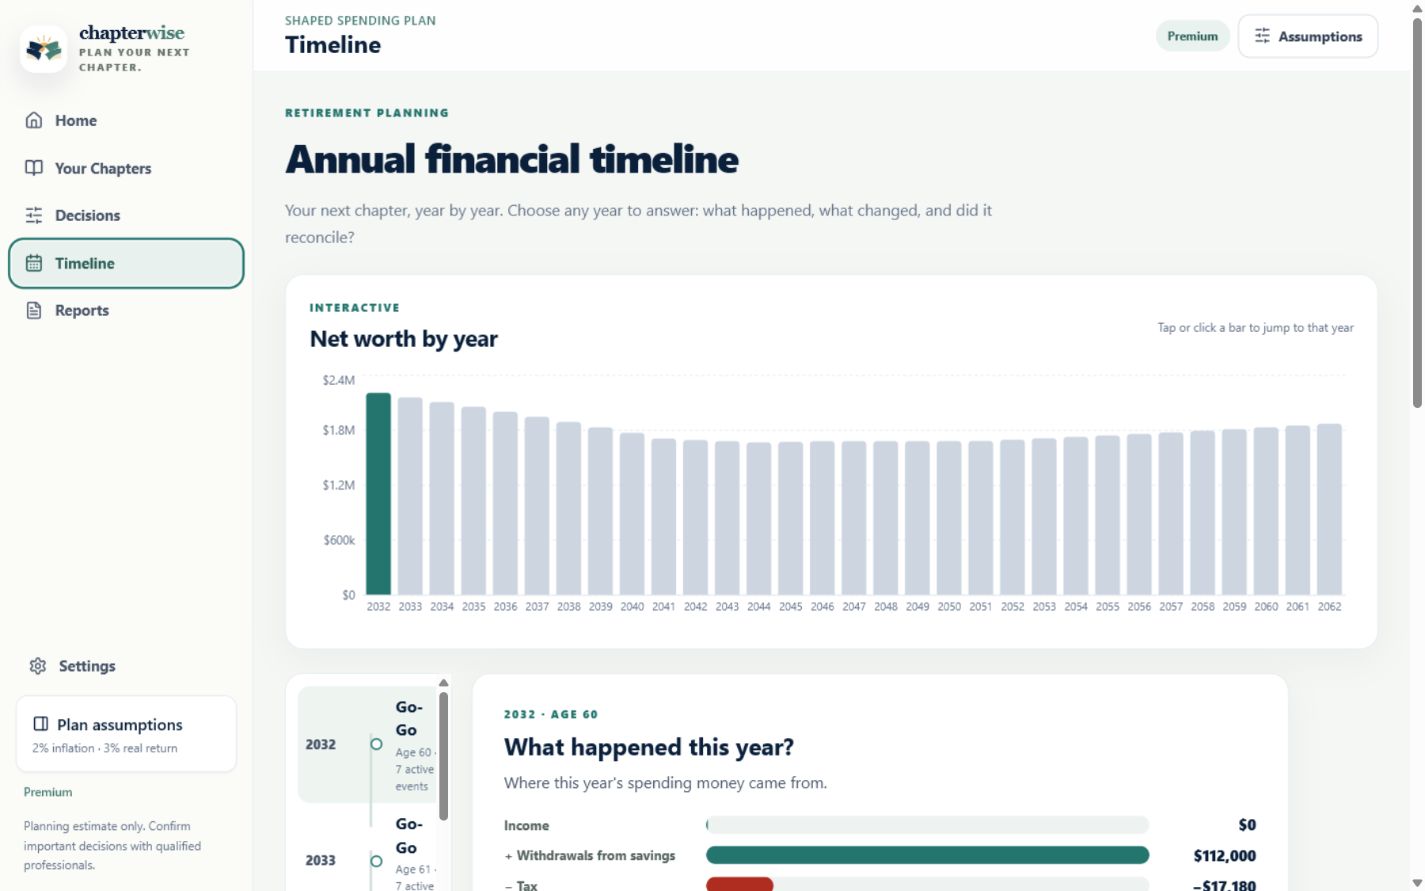
The RRIF minimum withdrawal is calculated as a percentage of the balance, and that percentage rises with age. A large RRSP left untouched until 71 converts into a RRIF with correspondingly large mandatory withdrawals, which can push total income high enough to trigger the OAS clawback, an outcome that's often avoidable with a bit of earlier planning.
None of this means converting early is automatically the right move. For some people, letting the RRSP keep growing untouched as long as possible is exactly right. The point isn't which choice is correct. It's that this turn in the story is worth planning for years ahead of the deadline, not the year it arrives.
A smaller first step
Try the decision before you sign up
This directional preview reuses the same illustrative logic as the homepage. It is not a recommendation or a personalized projection.
A turn, not an ending
The shift from RRSP to RRIF often gets treated like a bureaucratic formality, a form to fill out because the calendar says so. It's really one of the more consequential plot turns in the whole retirement story: the chapter where decades of saving finally starts becoming the income that funds the rest of the book.
This article is for general educational purposes and reflects rules believed accurate as of 2026. It isn't personalized financial or tax advice; RRIF rules, minimum withdrawal percentages, and tax thresholds should be confirmed with a financial or tax professional based on your own situation.