 chapter
Chapterwise retirement guide
The Slow Chapter Before the Fast One
The first $100,000 you save is the hardest. Here's why every $100K after it comes faster, and what that means for your retirement plan.
There's a chapter in every financial story that nobody tells you about in advance: the long, quiet stretch before your money starts working as hard as you do.
If you're in it right now, you already know the feeling. You're saving consistently. You're doing the "right" things. And yet the number in your account seems to inch forward at the same pace month after month, like a plot that refuses to move. It's not you. It's math, and once you understand it, this chapter starts to feel less like a grind and more like groundwork.
Why the first $100,000 takes the longest
Early on, you are the engine. Every dollar of growth in your account is essentially a dollar you put there yourself. A modest return on a modest balance produces a modest result, the kind of number that's easy to overlook next to your own contributions.
The math bears this out. Using a common illustration, someone saving $10,000 a year at a 7% average return, it takes roughly 7.8 years to reach the first $100,000. That's the slow chapter: years of steady effort before the story visibly picks up.
Why the next chapter moves faster
Here's the turn in the plot. Once that first $100,000 is in place, it starts pulling its own weight, and the pace changes without you doing anything differently.
Using the same saving pattern, the second $100,000 arrives in about 5.1 years , nearly 30% faster than the first, with no increase in effort. Keep going, and each milestone after that continues to arrive sooner than the one before it, purely because a larger balance generates more growth in dollar terms, even at the same rate of return. By the time a portfolio reaches $500,000, less than half of the total typically comes from what was actually contributed , the rest is growth doing the work.
Think of it less like a straight line and more like a story gaining momentum: the early pages set the stage, and the middle chapters start turning themselves.
A smaller first step
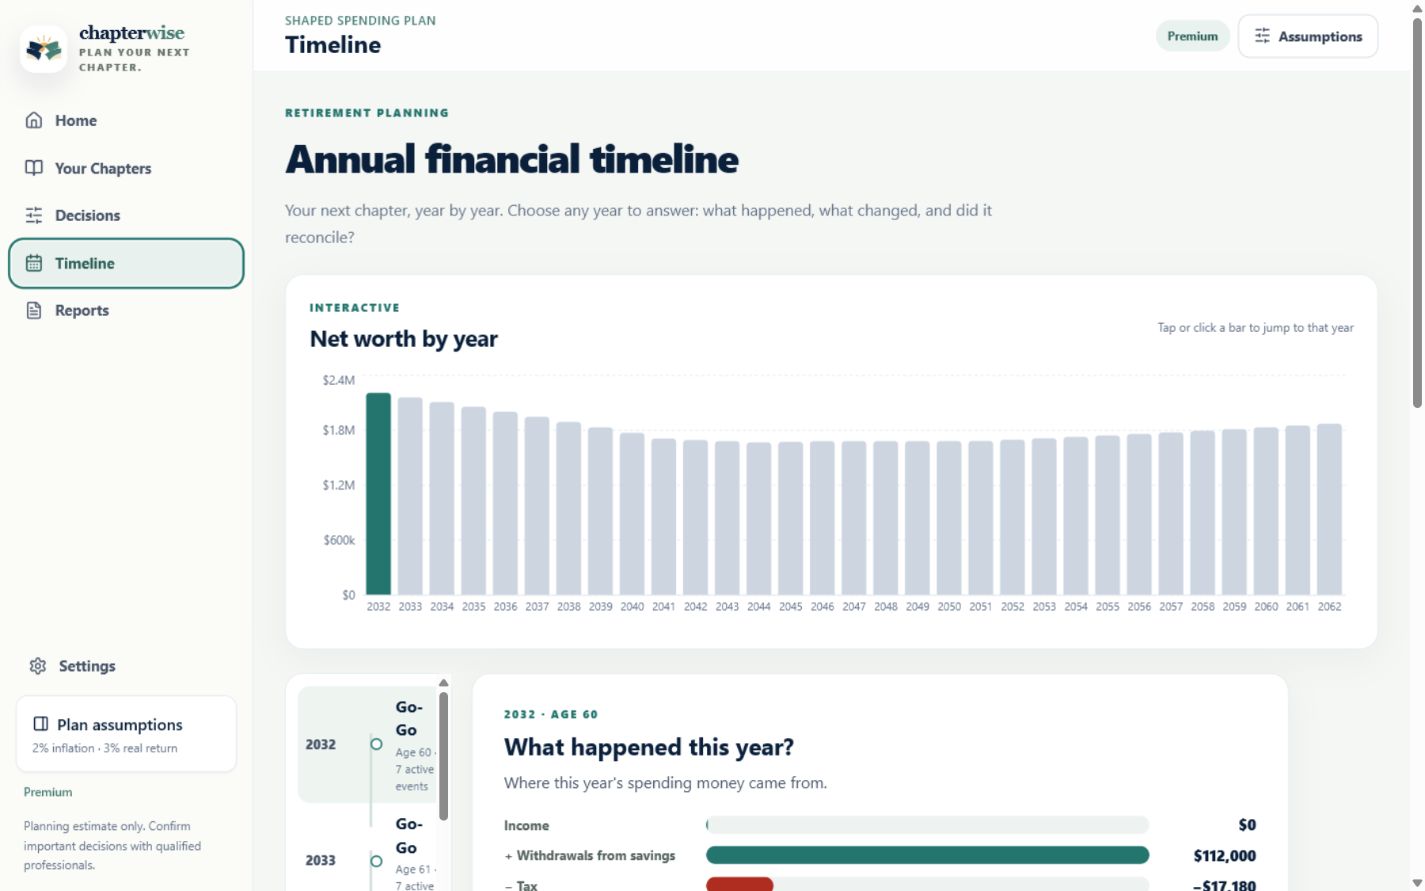
Try the decision before you sign up
This directional preview reuses the same illustrative logic as the homepage. It is not a recommendation or a personalized projection.
What this means for how you plan
This isn't a reason to chase bigger returns or take on more risk to speed things along; that usually backfires. It's a reason to trust the plan you're already writing.
A few things worth holding onto as you move through this stretch:
- The early years are supposed to feel slow. That's not a sign something's wrong; it's the nature of the chapter you're in.
- Consistency is the whole plot. Showing up with the same contribution, year after year, is what gets you to the point where compounding takes over.
- The milestone isn't the finish line. It's a turning point. Reaching $100,000 doesn't mean you're done with the hard work. It means the hard work starts sharing the load with time.
Your next chapter is closer than it feels
Every long story has a section that tests your patience before it rewards it. Building savings toward retirement is no different: the slow chapter is real, but it isn't the whole book.
If you're still in it, that's not a setback. It's the part of the story where the foundation gets laid for everything that compounds after it. Keep writing it. The pace picks up from here.
This article is for general educational purposes and reflects illustrative assumptions about savings and investment growth. It isn't personalized financial advice, and actual results will vary based on your own contributions, timeline, and market conditions.
Related chapters in this series
- The Chapter Where You Get to Take Your Foot Off the Gas
- The Years That Feel Like Nothing Is Happening
- The Worst Possible Day to Start, and It Still Worked Out